Three drugs. That is what changed Leerink Partners’ view of Bristol Myers Squibb.
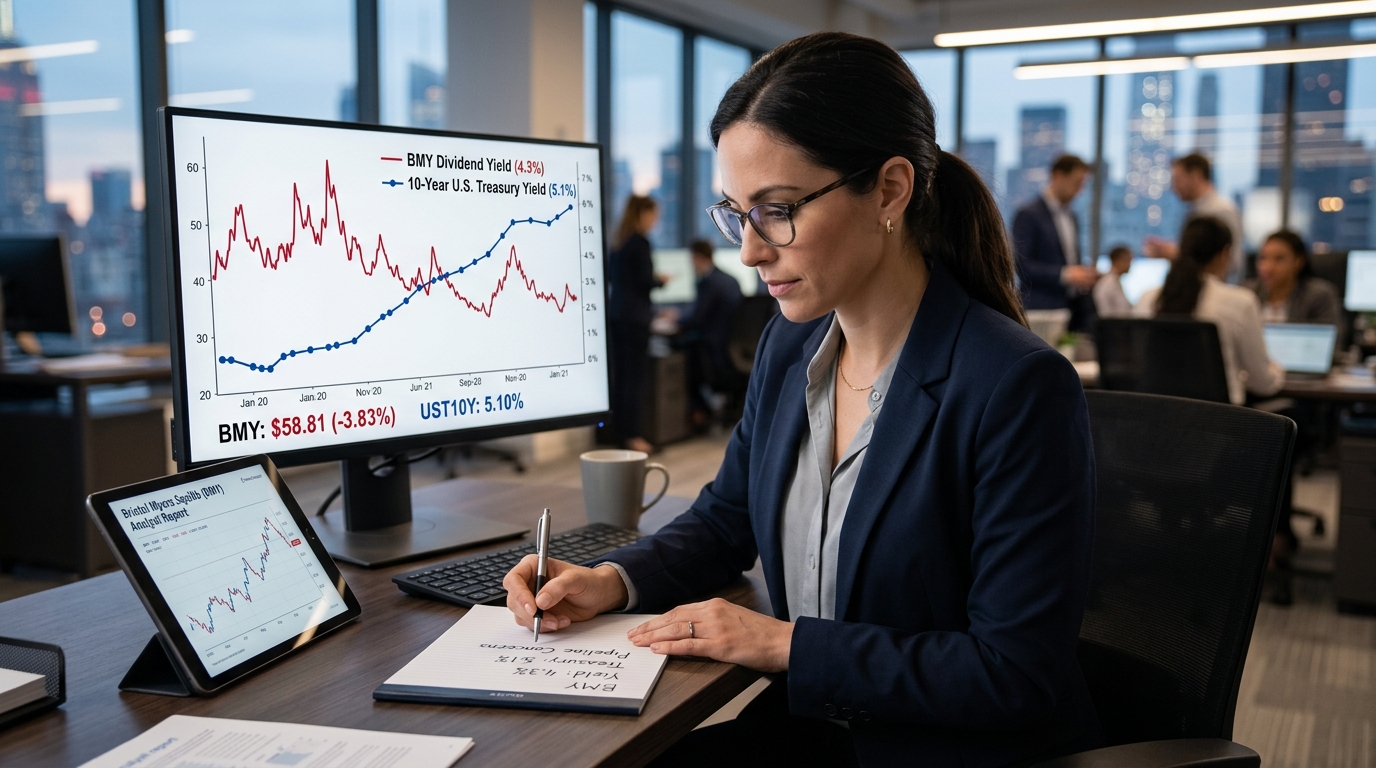
On Monday, October 5, analyst David Risinger downgraded BMY to Market Perform and cut his price target to $59, citing doubts on admilparant, milvexian, and Cobenfy. The price target fell 19% from $73. The stock closed at $58.81, down 3.83%.
Risinger wrote that Leerink conducted more detailed assessments of key pipeline candidates and concluded that it did not have enough conviction in strong results to recommend investors buy BMY shares. The firm cut its 2032 sales estimate for admilparant by 38% and for milvexian by 25%, and trimmed its 2032 EPS estimate by 11% to $4.96.
For income-focused investors, the relevant question is not whether Leerink is right about clinical outcomes. It is whether BMY’s income stream still justifies the risk of holding it in a conservative portfolio.
The Yield Comparison That Matters Now
BMY carries a forward dividend of $2.52 per share, yielding approximately 4.3%. The annual rate of $2.52 per share marks the 17th consecutive year of dividend growth and the 94th consecutive year the company has paid one. That history is real. So is the problem.
The 10-year Treasury yielded 5.31% on October 5. With the 10-year above 5% and core PCE around 3%, nominal yields now exceed current inflation by roughly 2%. A BMY shareholder takes on pipeline uncertainty, Medicare price negotiation risk, and a patent cliff approaching on Eliquis and Opdivo, for a yield roughly 100 basis points below what a 10-year Treasury offers with no credit risk at all.
That spread used to run in the other direction. For most of the past decade, BMY’s dividend was competitive and Treasuries paid almost nothing. That trade no longer exists.
The Valuation Argument, and Its Limits
Bristol Myers has drawn attention as a value stock, with a forward price-to-earnings ratio near 9x. That compares favorably to Johnson & Johnson and Merck, which typically trade at much higher forward earnings multiples. The low multiple reflects what the market already knows: revenue from legacy blockbusters is shrinking, and the replacement pipeline is now in question.
As loss of exclusivity approaches in the latter half of the decade, market participants require high confidence in new drug development to offset impending revenue declines, making any negative reassessment of pipeline prospects particularly damaging to valuation multiples. Leerink’s downgrade does exactly that. A stock at 9 times earnings is cheap only if those earnings hold. If admilparant or milvexian disappoint in coming readouts, estimates come down, and that multiple expands without the stock moving.
Bristol Myers’ most recent quarterly update showed the company raised its 2026 revenue and non-GAAP earnings outlook, so the downgrade is not tied to a fresh earnings warning. Third-quarter 2026 results are due October 29. That date provides a near-term checkpoint, but clinical data, not quarterly revenue, will decide whether the discount is deserved or a trap.
What Conservative Portfolios Should Do
BMY still earns consideration, but not the same consideration it earned a year ago. The dividend is covered, the payout ratio is manageable, and 94 years of consecutive payments carries weight. The issue is opportunity cost. Income investors who built a position when Treasuries yielded 2% were accepting pipeline risk in exchange for income that was genuinely scarce. At 5.3% on the 10-year, that trade requires a more deliberate choice.
Existing holders should hold through the October 29 earnings call and watch for any update on pipeline timelines. Adding here, before clinical readouts on three disputed programs, stretches the risk profile of what should be a conservative income holding. The dividend remains intact today. Whether it still earns its place depends on data that has not been read yet.