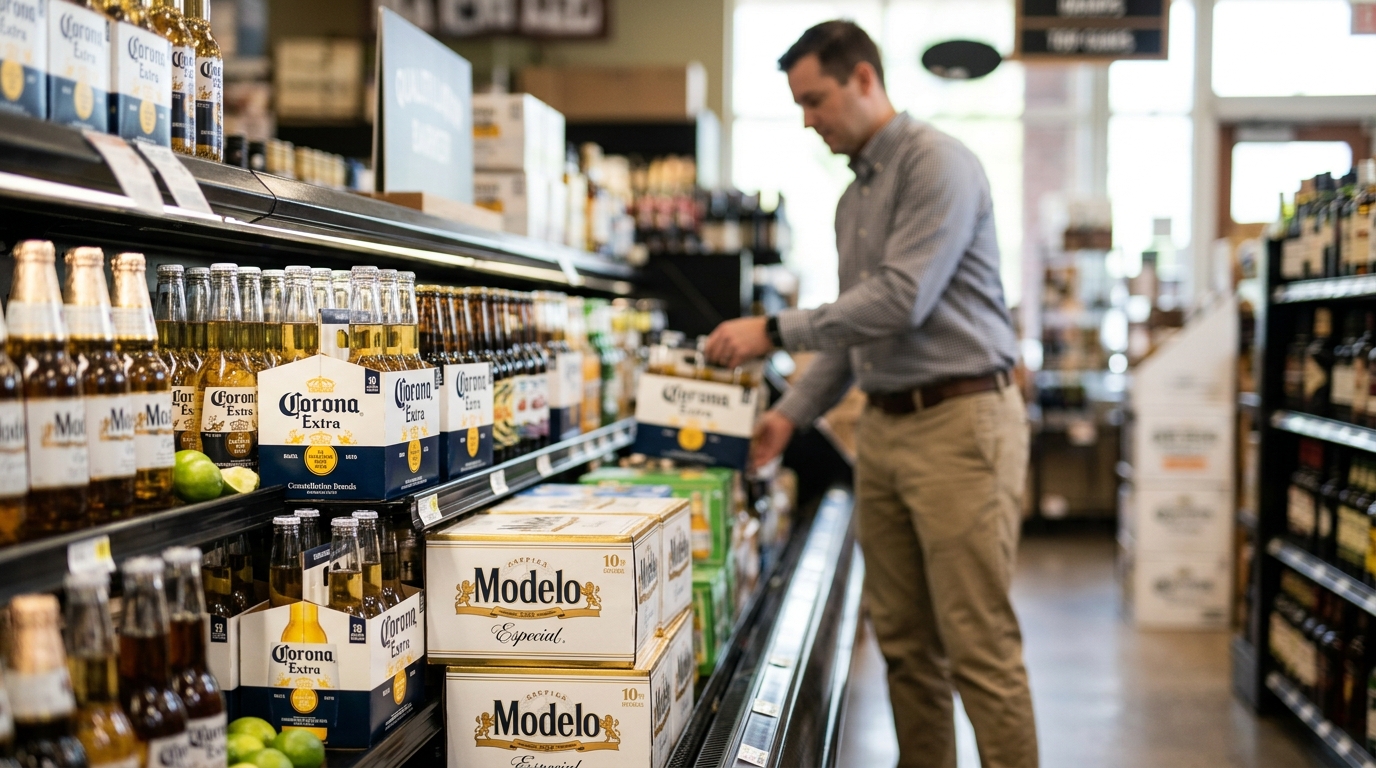
Modelo and Corona remain the top-selling imported beers in the United States. Constellation Brands, which holds the U.S. rights to both, reports fiscal second-quarter results on October 6, after the close. The stock closed at $111.54 on October 2, matching its 52-week low, at about 9.6x forward earnings. The average analyst price target is $163, implying roughly 47% upside.
That gap did not exist two years ago when STZ traded above $250. Understanding what broke the stock is the first step toward understanding whether October 6 can begin to repair it.
The Business
Constellation’s beer division is the profit engine. Modelo Especial is America’s top-selling beer brand by dollar sales at retail. The company also owns Pacifico, Victoria, Robert Mondavi Winery, and Casa Noble tequila, but beer drives the income statement.
The company’s challenge is demographic. Hispanic consumers account for nearly half of Constellation’s U.S. beer sales. Beginning in 2025, that group pulled back. CEO Bill Newlands cited fewer social occasions and lower spend per trip, driven by immigration enforcement concerns and broader economic pressure. In September 2025, the company cut its fiscal 2026 comparable EPS guidance from $12.60-$12.90 to $11.30-$11.60 per share.
Why Wall Street Is Paying Attention
The headwind is well documented, which means it is also largely priced in. Beer shipment volumes fell sharply at points in fiscal 2026, and management has argued the rate of pressure in higher-Hispanic zip codes moderated as fiscal 2026 progressed. Pacifico and Victoria remained bright spots, with each posting double-digit depletion growth in fiscal 2026 periods even as the flagship brands absorbed pressure. Constellation has also pointed to broad geographic share gains, including portfolio share gains in 49 of 50 states.
Analysts expect Q2 revenue of roughly $2.57 billion and EPS near $3.62. Constellation has beaten estimates in recent quarters, and the stock is trading as if solid execution is no longer enough. Low expectations meeting solid execution is the recurring pattern heading into Monday.
What’s Driving the Opportunity
At 9.6x forward earnings with a 3.65% dividend yield, the stock is priced for permanent damage to its consumer franchise. Management has discussed multi-year cash generation targets and continued investment behind beer capacity, including a third brewery near the port of Veracruz that remains under development.
The rate of deterioration has clearly slowed in the company’s own commentary, particularly in retailer geographies with higher Hispanic exposure. October 6 is the next data point on whether that pattern continued through the summer.
What Could Go Wrong
The consumer pressure may not have troughed. If Q2 beer depletions come in below expectations and management signals continued full-year caution, the stock has limited support below $111. Aluminum tariffs remain an input cost problem. The company has cited aluminum tariffs as a margin headwind, and it has previously disclosed that a meaningful share of its beer volume is packaged in cans. A guidance cut to its multi-year cash flow targets would likely push the stock to fresh lows.
The Bottom Line
Constellation owns the most popular beer brand in America, generates substantial free cash flow, and pays a growing dividend. The stock trades at levels implying the core demographic challenge is both severe and permanent. Evidence through early 2026 pointed to stabilization. Monday’s report either confirms that trajectory or restarts the decline. At about 10x forward earnings with roughly 47% analyst upside, the risk-to-reward case is compelling enough to watch closely what management says on October 6 about consumer trends heading into the holiday quarter.