The French National Assembly begins debating Prime Minister Sébastien Lecornu’s 2027 budget on Tuesday, October 13. The parliamentary theatre matters less this week than the number flickering in the bond market: the gap between what France pays to borrow and what Germany pays.
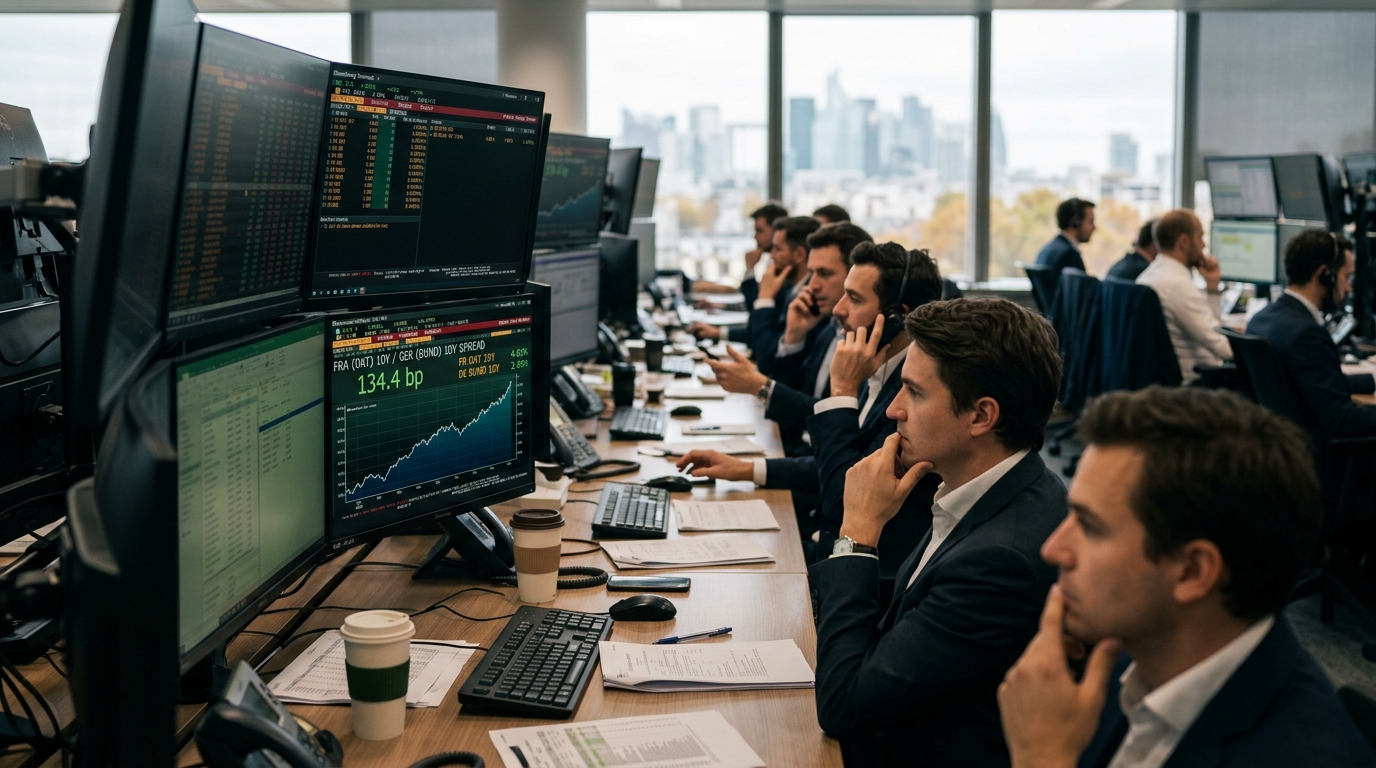
As of October 7, the OAT-Bund spread stood at 134.4 basis points, with the 10-year French OAT yielding 4.83% against 3.49% for the German Bund. France’s 10-year yield climbed to around 4.92% on October 6, its highest level since 2002. The peak reached 146.9 basis points on October 2 before pulling back. That retreat has not resolved anything.
What the Budget Actually Does
The government’s plan aims to reduce the deficit from a projected 5.4% of GDP in 2026 to 5% by 2027, through approximately €54 billion in savings from a mix of tax hikes and spending cuts. Even if the planned fiscal consolidation is delivered, it would slow rather than halt the rise in debt. That distinction is the market’s central complaint. Investors are not being asked to price a recovery; they are being asked to price a deceleration in deterioration.
The budget now enters the parliamentary phase. Full debate in the National Assembly on the revenue section begins October 13, before moving on to spending measures and the social security budget. Various procedural steps will fall in November and December before the hard deadline for adoption at year-end. Lecornu’s government has no majority, a fact the market already lived through once when Lecornu used Article 49.3 to push the 2026 budget through without a vote.
What the Market May Be Missing
The bond spread is not simply pricing parliamentary chaos. It is pricing a structural constraint that the budget itself acknowledges: higher spending on interest payments, pensions, and social benefits is coinciding with the expiry of temporary tax measures and weaker revenue growth, with debt-servicing costs expected to rise sharply next year.
There is also a ceiling problem. The ECB’s Transmission Protection Instrument is unlikely to be implemented, because France does not qualify on current criteria. France is under a European Union excessive deficit procedure, which is one of the criteria the ECB considers when assessing eligibility. The TPI can only purchase bonds in countries whose yield widening is judged “unwarranted” by fundamentals. When Lagarde speaks Tuesday and Wednesday, listen for any signal about whether the ECB is reassessing that position. The probability is low, but the stakes are not.
Where It Shows Up
Domestic banks have struggled in this environment given concerns about political uncertainty and high government debt. The divergence between French and European bank CDS is the cleaner signal: investors are not shifting risk appetite on European financials broadly. They are shifting it on France specifically.
Banks and insurers, heavily exposed to domestic sovereign bonds, suffer portfolio mark-to-market losses when rates rise, which can weigh on credit distribution capacity and prudential requirements. AXA, as France’s largest insurer and a significant holder of domestic sovereign paper, sits in the same transmission channel.
Risks and Counterpoints
The spread level is particularly high relative to France’s actual fiscal position. French debt-to-GDP is lower than that of Italy and Greece and only moderately higher than that of Belgium and Spain. Yet the premium the market demands for holding OATs over Bunds has moved to the top tier in the eurozone. That gap between fundamentals and pricing is the bullish case: if parliamentary debate passes without immediate crisis, a partial spread compression is plausible.
The bearish case is simpler. Moody’s said on October 2 that the outlook for France passing its 2027 budget is highly uncertain as a presidential election approaches and fragmentation is likely to persist afterwards, complicating fiscal consolidation.
What to Watch Next
Moody’s last acted on France’s rating on April 10, 2026. The next scheduled review date is October 23, 2026. Moody’s currently holds a negative outlook on France’s Aa3 rating, meaning the next move is more likely to be a downgrade. Twelve days sit between Tuesday’s debate opening and that review. Watch whether the OAT-Bund spread widens back toward 150 basis points as parliamentary headlines accumulate, or holds closer to 130 as markets price in procedural calm. The spread is the referendum; everything else this week is commentary.