Software Stocks Hit 2026 Highs as the Market Cools
Rotation out of chips and into enterprise software is accelerating, even as yields rise.
The market is offering a rare edge case right now: a group making fresh year-to-date highs while the broader market struggles with rising Treasury yields. That group is software, and the divergence deserves attention before the rest of the market figures out what it means.
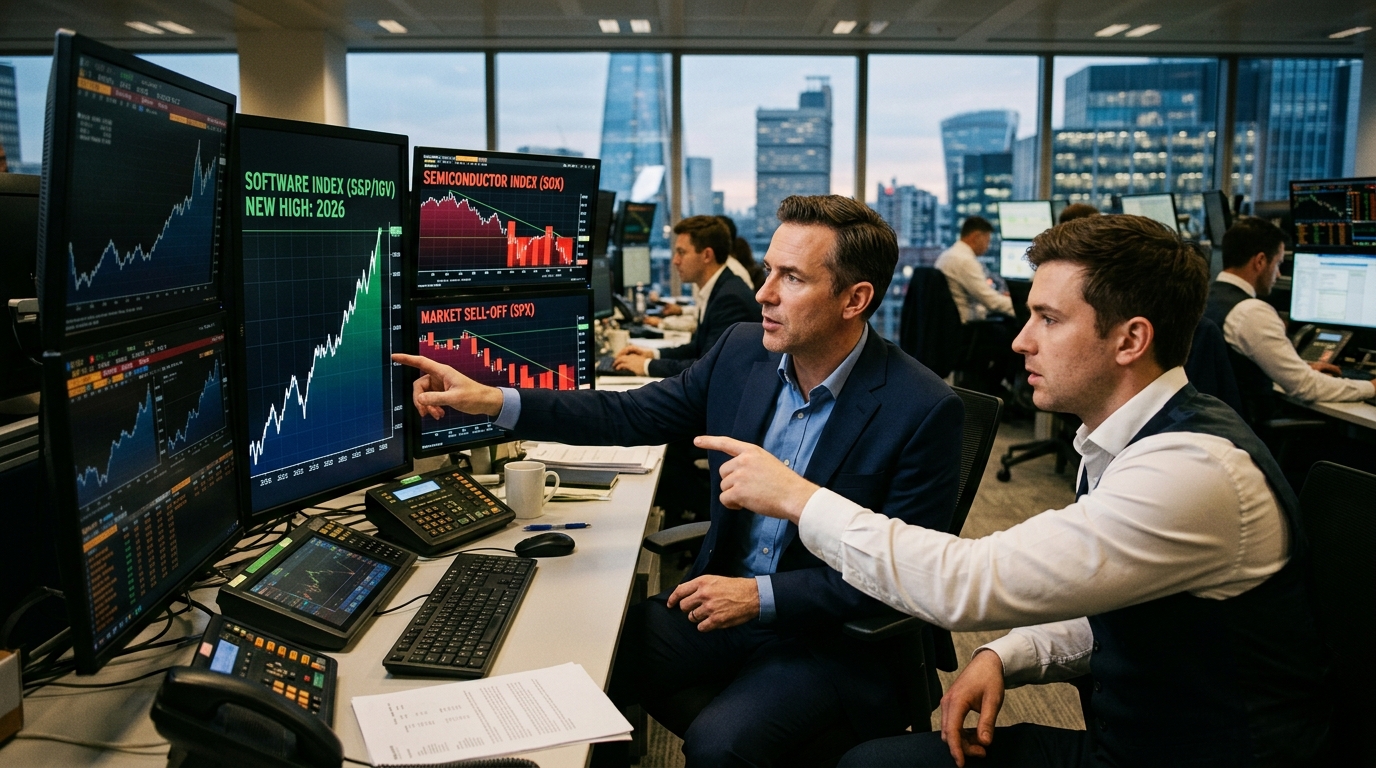
Reuters reported that the S&P 500 software and services index rose 1.3% on Tuesday, October 6, 2026, to its highest level since November 2025, after posting its biggest quarterly gain in the July-to-September period since the second quarter of 2020. The magnitude of that quarterly move matters as much as the headline level. This was not a slow drift higher. It was a decisive move.
What Changed
Software spent the first half of 2026 as the AI trade’s most visible casualty. Reuters described a selloff that was widely dubbed the “SaaSpocalypse,” tied to fears that companies could use AI to build applications in-house more cheaply, and reported the software index fell more than 26% from late January to a low in April. That fear turned out to be premature. Reuters quoted Rebecca Wettemann, CEO of technology research firm Valoir, saying the fear ran ahead of evidence, as vendors were reporting customer uptake as AI adoption moved beyond the experimental stage.
The earnings data backs that assessment. Reuters cited LSEG data showing the sector’s expected annual earnings growth rate for 2026 has climbed to 20.6%, up from 13.8% at the end of March. That is not a small revision. It reflects a fundamental reassessment of whether AI displaces software revenue or amplifies it.
Reuters also quoted Adam Turnquist, chief cross-asset strategist at LPL Financial: “AI has been more of an enabler for a lot of these software companies, more than a disruptor.” Other strategists cited by Reuters see “a window here for outperformance in software over semiconductors.”
The Rotation Trade
Software stocks staged one of the sharpest rotations in years while chip stocks rolled over. Reuters reported the software index is up about 5% this year, while the Philadelphia SE Semiconductor index has surged 87.5% in 2026 but is well off its highs. The valuation gap that opened during chip euphoria is now closing from both ends simultaneously.
Stocks on the Radar
Microsoft (MSFT) is the highest-conviction name in the group. On October 5, 2026, Melius Research upgraded the stock to Buy with a $665 price target, and media reports tied the call to rising demand for trusted platforms and cybersecurity as AI risk debates intensify. The fundamental picture is equally compelling: Reuters reported Microsoft said Azure revenue growth accelerated to 43% in its most recent quarter. In Microsoft’s FY 2026 Q4 materials and filing, the company reported commercial remaining performance obligations rose 84% to $678 billion. Fiscal Q1 2027 earnings are expected October 27, and that report is the near-term catalyst worth monitoring.
Salesforce (CRM) offers the cheapest entry in the enterprise software cohort. In its fiscal 2026 fourth-quarter release, Salesforce said Agentforce and Data 360 annual recurring revenue exceeded $2.9 billion, up over 200% year over year. Against that backdrop, the stock’s valuation is meaningfully below many large-cap software peers, which is why CRM reads as the value option for investors who want software exposure without paying premium growth multiples.
HubSpot (HUBS) is the name that requires the most caution right now. Raymond James downgraded HUBS to Market Perform from Outperform, citing near-term demand dynamics and potential packaging changes that could weigh on net new growth in 2027. The downgrade signals that not every name in the software group is participating equally in this recovery.
Risk Dashboard
The central tension in this trade is that software is making new highs against a backdrop of rising yields, which are suppressing the rest of the market. That dynamic can persist, but it can also break quickly if yields push high enough to tighten financial conditions materially. Reuters quoted Zacks Investment Management’s chief market strategist Brian Mulberry saying the real test for software stocks could come in the second half of 2027, when more data-center capacity might make AI coding a bigger competitive threat.
Trader’s Action Plan
Software’s breakout to 2026 highs, while semiconductors sit well off their peaks, is the clearest sector leadership signal in months. Microsoft is the best-supported name given the Azure acceleration and the October 27 earnings catalyst. Salesforce is the value play for those who want sector exposure at a discount. Avoid HubSpot until the Raymond James growth concerns are resolved by an actual earnings report. Watch Treasury yields daily: software’s relative strength holds as long as the rotation out of rate-sensitive cyclicals continues. If 10-year yields spike through a new multi-year high, reassess position sizes before adding new exposure.