Governor Christopher Waller flew to Istanbul on Thursday and said what the bond market had already suspected: more rate hikes are coming, October is likely a skip, and December is the destination. The question for traders heading into next week is not whether the Fed moves again. It is which sectors get squeezed hardest before it does.
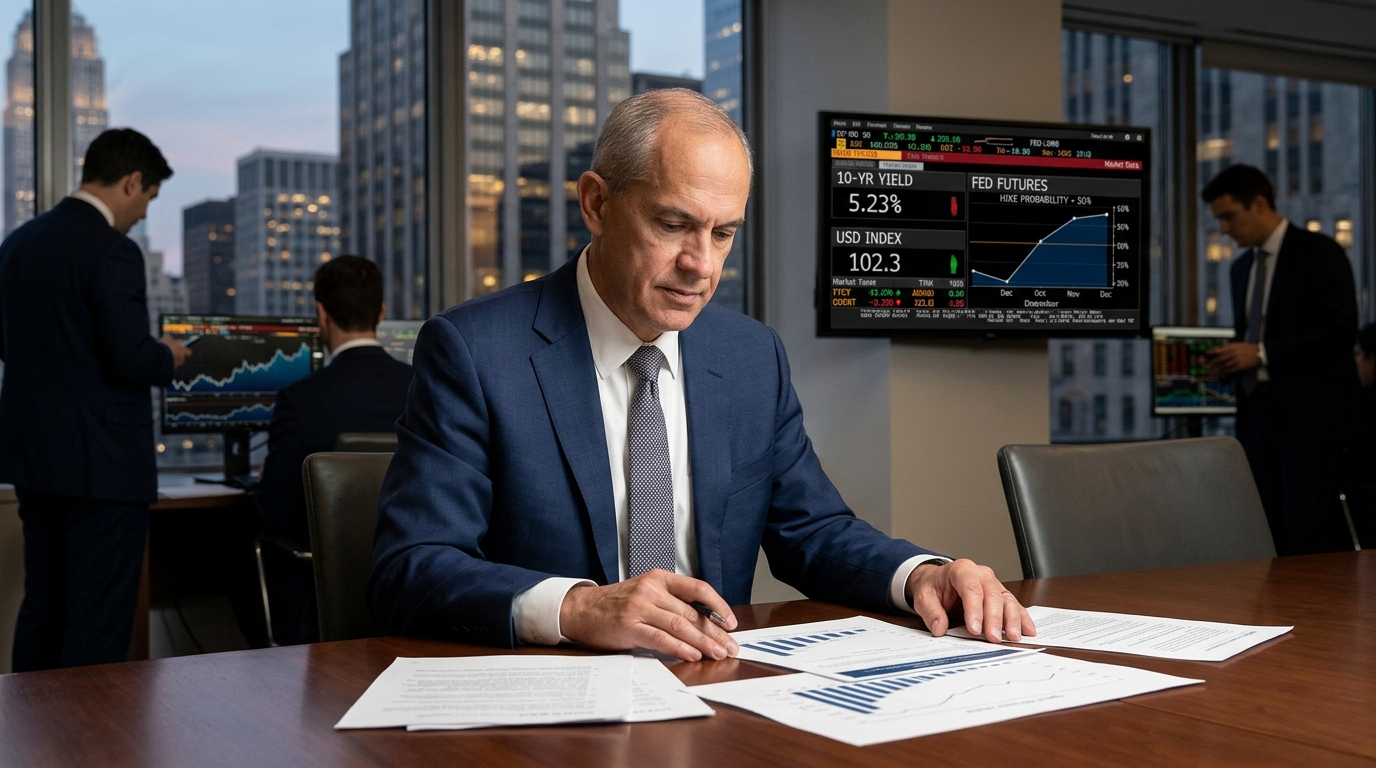
The numbers Waller pointed to are themselves instructive. Futures markets are still leaning toward additional tightening later this year, even as October odds have drifted lower. The Fed raised the target range to 3.75%-4.00% in September, and the September minutes said most participants assessed that another increase would likely be appropriate by year-end.
Three forces are driving that hawkish consensus. First, the Middle East conflict has kept oil prices elevated. Second, AI infrastructure spending is adding demand pressure in parts of the supply chain. Third, another round of tariffs remains a live risk. Each of those on its own is manageable. Stacked, they kept Waller from offering any comfort to rate-sensitive longs.
The 10-year Treasury pulled back to 5.23% after touching about 5.36% earlier in the week, near its highest level since 2002. That retreat is small comfort. Yields are still high enough to keep financial conditions tight, and the rate path remains data-dependent. The long bond finished the week around 5.61%.
Where the Pressure Lands
The dollar index sits near 102.3, an 18-month high. EUR/USD has been pushed near 1.12, with the euro’s 57.6% weight in the DXY making Europe a key driver of greenback strength. USD/JPY holds near 158, supported by a Fed-BoJ rate gap that remains roughly 2.75 percentage points wide.
For equities, the damage map is familiar but the magnitude is what matters at 5.23%. Schwab’s current sector rankings have real estate rated least favored and utilities less favored. REITs borrow heavily, making elevated financing costs a direct drag on cash flows, not a theoretical risk. The iShares Core U.S. REIT ETF has underperformed the broader market as rates pushed higher again into October. Utilities face the same capital spending squeeze. Financials, by contrast, carry a more-favored rating: banks can earn wider net interest margins as rates climb, provided credit quality holds.
What to Watch
Waller was clear that hikes do not need to come at consecutive meetings. That framing keeps the October 27-28 meeting technically live while leaving December as the higher-conviction window for another move. The CPI reading due before that October decision now carries disproportionate weight: a hot number could lift October odds, which would compress rate-sensitive sectors further and give the dollar another push higher.
The highest-conviction positioning into next week favors financial sector exposure over real estate and utilities, a long dollar bias against the euro and yen, and caution toward small caps, which face a double burden from higher borrowing costs and softer consumer demand. The 10-year at 5.23% is not yet the ceiling. If next week’s data validates Waller’s outlook, the path of least resistance for yields remains higher, and the sectors priced for relief will not find it before December.