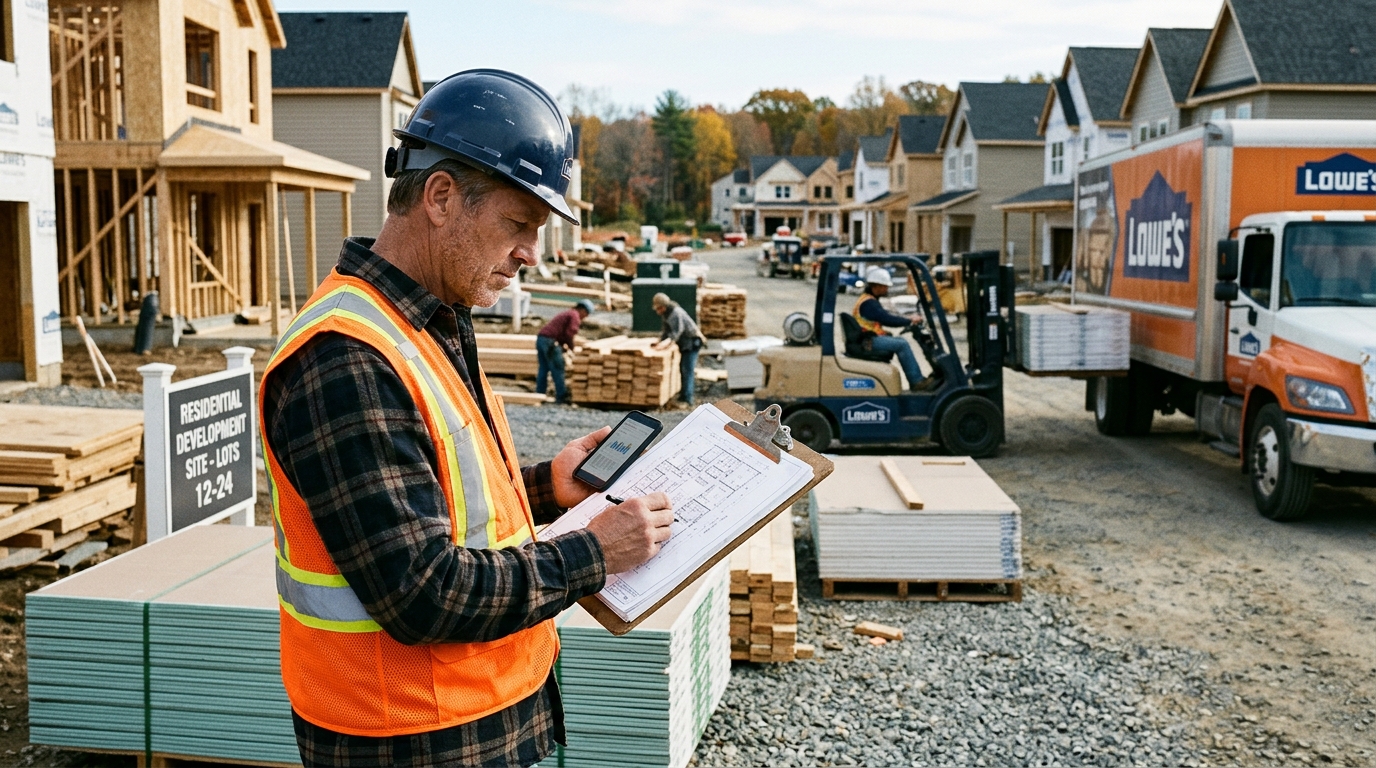
Two numbers land before the opening bell on Wednesday that together tell you more about housing than anything else scheduled this week. The Census Bureau releases October new residential construction data at 8:30 AM ET, and Lowe’s reports its third quarter earnings at the same hour. Supply and demand, in one session.
What the Data Is Walking Into
September housing starts came in at a seasonally adjusted annual rate of 1.221 million, 5.2% below the revised August estimate of 1.288 million and 7.4% below the year-ago pace. That missed the 1.30 million consensus by a wide margin. Homebuilding activity rounded out the third quarter with a third successive month of declines, and single-family starts fell to their lowest level in a year.
Permits in September were at a seasonally adjusted annual rate of 1.400 million, 0.2% below the revised August rate and 3.0% below September 2025. Permits matter because they lead starts by one to three months. A flat permit count after three months of falling starts is a slim argument for stabilization, not a reason to call a bottom outright.
The demand backdrop is not helping. Existing home sales fell to their slowest pace in more than 16 years in October, with mortgage rates back above 7% since mid-September and home prices still elevated keeping buyers on the sidelines. Contract closings fell 5.5% to an annualized rate of 3.75 million, according to the National Association of Realtors. Sales declined across all four regions.
The Rate Anchor That Will Not Move
Freddie Mac’s November 12 survey put the weekly 30-year average at 7.11%, down from 7.18%. Four weeks of modest declines. The benchmark 10-year Treasury yield was around 5.09% early Wednesday as Wall Street awaited the release of the latest FOMC minutes. The Mortgage Bankers Association forecasts the 10-year will average 5.1% in the fourth quarter of 2026, which would likely keep the 30-year mortgage rate averaging 7.3% through year-end.
That is the structural ceiling on builder demand. Builders can cut prices and buy down rates, and the largest ones are doing exactly that, but the volume effect is limited when the entry-level buyer has effectively been priced out of a fixed-rate mortgage at these levels.
Lowe’s as the Demand Gauge
Lowe’s Q3 results are due November 18; Wall Street expects EPS of $2.88 on revenue of about $22.4 billion. The bar is low and falling: 27 downward EPS revisions and 25 revenue revisions reflect cautious market expectations amid macroeconomic pressures. In Q2, total sales were $26.0 billion, but comparable sales grew only 0.2%, driven by Pro and home services strength and a 15.7% jump in online sales, partially offset by persistent DIY macro pressures. If that DIY weakness deepened into October, the same-store sales line is the number to watch, not the headline revenue figure that includes the Foundation Building Materials acquisition.
Homebuilder Stocks: Fade or Floor
XHB traded between $98.96 and $102.07 on Tuesday, closing near $99.09. The ETF’s 52-week range spans from $91.87 to $123.13, meaning it sits roughly 19% below its high with a tested floor roughly 8% lower. The October permit count is the clearest signal for positioning. Permits holding at 1.40 million or above, combined with any sequential recovery in October starts, would support the argument that September was a weather- and rate-shock-driven trough. Permits rolling toward 1.35 million or below resets that thesis.
Trader’s Action Plan
DHI, LEN, and PHM move on the starts release even before Lowe’s opens its call. Watch the single-family permit line specifically. That is where builder order pipelines are priced. A reading that holds September’s 845,000 single-family authorization rate steady favors a relief trade in XHB toward the $104 to $106 range. A step-down breaks the modest stabilization argument and puts pressure on builder margins heading into 2027 guidance season.
On Lowe’s: the stock has gained over 25% in the past month, so it is carrying momentum into a quarter with a 6% expected EPS decline. At about 18x forward earnings, shares are at a discount compared to Home Depot, which limits the downside on a modest miss. A same-store sales line better than flat on the DIY side, however, would confirm that the housing freeze is thawing at the margin. That is the detail that matters for the sector read, not the adjusted EPS beat or miss against a consensus that has already been revised 27 times lower.