Why This Stock Now
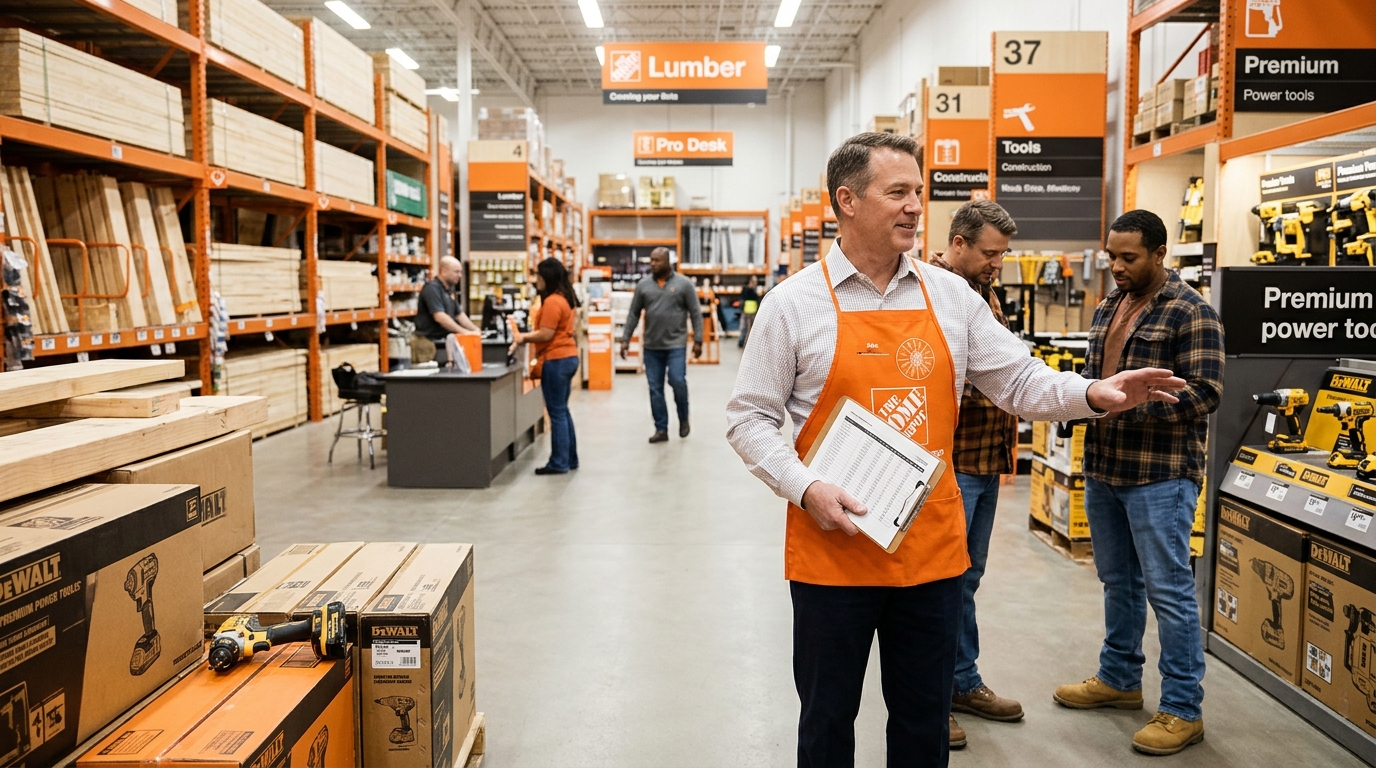
Home Depot reported Tuesday and the stock dropped about 2.5% anyway. That reaction, in a week when the broader market is under sustained pressure, leaves shares at $337, about 15% below the 52-week high of about $398. The dip arrives the same day the company announced its next CEO and posted its strongest comparable sales growth in four years. Sometimes the market hands you a re-entry the news cycle does not fully explain.
The Business
The Home Depot reported sales of $43.4 billion for the third quarter of fiscal 2026, an increase of $2.0 billion, or 4.9% from the third quarter of fiscal 2025. Comparable sales rose 2.2%, the strongest comp growth in four years, with 13 of 16 merchandising departments positive and sales leveraging its digital platforms up about 13%, the sixth consecutive quarter of double-digit online comp growth.
What makes the result striking is the backdrop. Morgan Stanley’s Simeon Gutman asked about the sustainability of growth given housing remains frozen with existing home sales near a 16-year low. Management noted that housing turnover has not moved in four years, yet Home Depot has posted nine straight quarters of positive comparable sales among Pro customers, all coming from share gain. That is not a housing recovery story. That is a market share story, and it is a more durable one.
Why Wall Street Is Paying Attention
The leadership change matters more than the market’s initial reaction suggests. Home Depot announced that its chief financial officer, Richard McPhail, will become CEO of the company, succeeding Ted Decker, effective Sunday, November 23, 2026. During his tenure as CFO, McPhail oversaw several major acquisitions, including HD Supply, SRS Distribution, GMS, Construction Resources and Mingledorff’s, building the professional contractor ecosystem that is now delivering those nine consecutive quarters of positive comps in the Pro business. He understands exactly where the revenue comes from.
Big-ticket transactions over $1,000 grew 4.5%, supported by demand in power equipment and appliances. That is the category most sensitive to housing activity, and it is growing. The average analyst rating is Moderate Buy with an average price target of $378.54. Institutional investors own 70.86% of the company’s stock.
What Could Go Wrong
One fair objection is that there is no clear near-term return to the housing conditions that historically helped fuel big-ticket home improvement. Mortgage rates remain elevated, roofing has been under pressure at SRS with sharp pricing in that market, and gross margin contracted 60 basis points in Q3 due to mix and acquisition-related effects. At a P/E of about 23x with earnings growing in the low single digits this year, the stock is not deeply discounted.
The Bottom Line
Home Depot does not need a housing recovery to compound shareholder returns right now. It needs to keep taking share among professional contractors and to execute digitally, both of which are working. The new CEO was the architect, as CFO, of the acquisitions creating that pro ecosystem. When existing home sales eventually normalize, years of pent-up renovation demand represent a release valve with real magnitude. Even a modest improvement in existing home sales can unlock deferred renovation demand in kitchens, flooring, roofing, and structural repair, categories where Home Depot maintains strong market share. The stock at $337 prices in continued paralysis. Any thaw changes the picture materially, and Richard McPhail takes the top job Sunday.