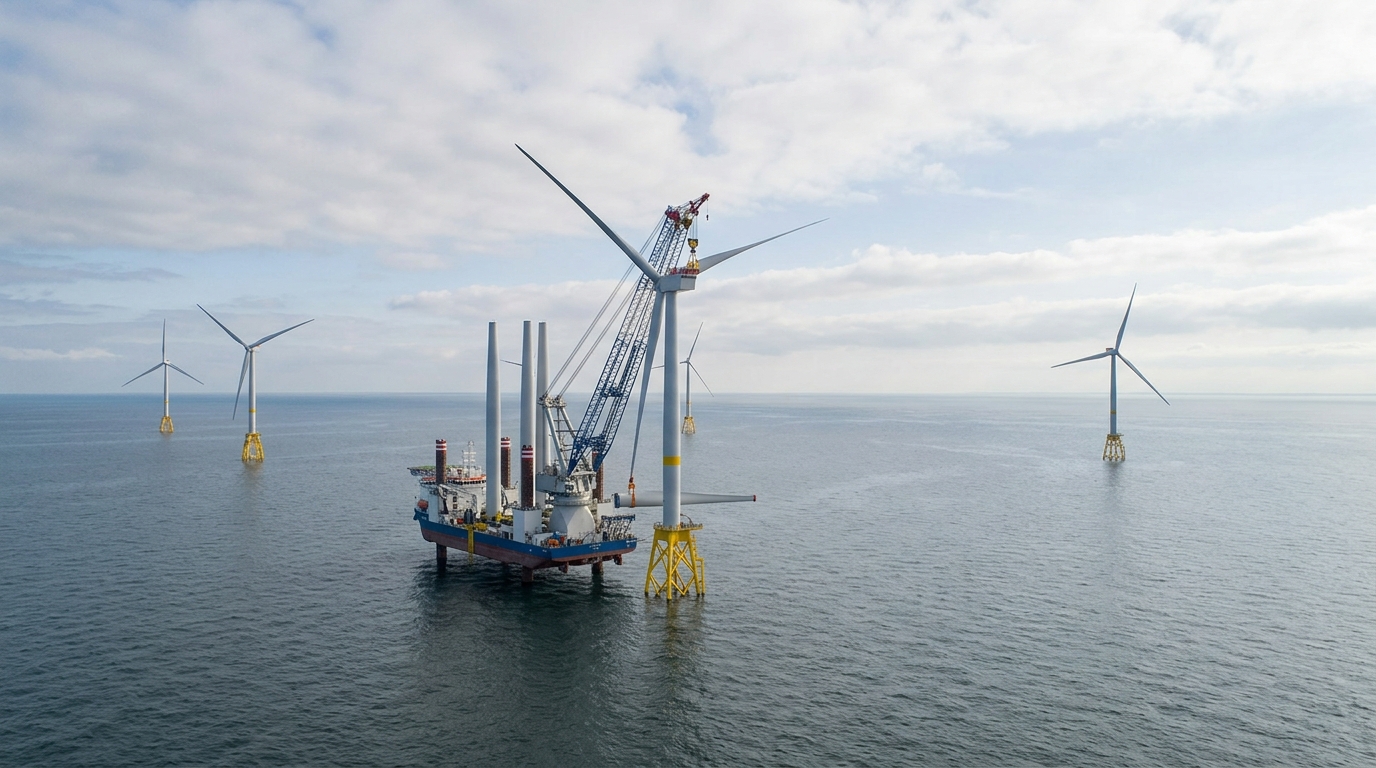
This morning, Spanish daily Expansión reported that Iberdrola is preparing to launch the sale of up to 49% of its East Anglia Two offshore wind project, valued at around €5 billion. Bank of America and BBVA have been hired as financial advisers for the potential sale. The asset sits inside Iberdrola’s ScottishPower subsidiary and is a 960-megawatt farm scheduled to begin generating power in 2028.
The deal follows a clear template. It would run along similar lines to the East Anglia Three transaction with Masdar, which involved a co-investment of €5.2 billion in the 1.4 GW farm off the Suffolk coast. Before that, Macquarie’s Green Investment Group took a stake in East Anglia One. Capital recycling through strategic partnerships and asset farm-downs has become a critical financing mechanism for offshore wind developers, enabling them to fund massive project pipelines in a tight investment climate, by selling equity stakes in operational or late-stage development projects to de-risk balance sheets and free up capital.
Iberdrola is not alone. Ørsted completed the sale of a 50% stake in its massive 2.9 GW Hornsea 3 project to funds managed by Apollo in December 2025. That broader divestment program generated about 46 billion Danish kroner in proceeds across its 2025 to 2026 partnership and divestment programme, above its original target. The pattern is consistent across European power: build the asset, bring in a financial partner at scale, redeploy the cash.
The Question Income Investors Should Actually Ask
Here is where it gets consequential for anyone holding Iberdrola for its yield. The company’s strategic plan has established a minimum shareholder remuneration of €0.64 per share for the 2025-2028 period, and Iberdrola has already fulfilled ahead of schedule its commitment to set a dividend of between €0.61 and €0.66 per share by 2026. On paper that is encouraging. The test is whether those distributions are coming from the business earning more or from the business shrinking its asset base to pay out.
The East Anglia Two sale helps answer that question, and the answer is mixed. Historically, generation has provided around 65% of Iberdrola’s EBITDA, but the company expects regulated networks to account for about 55% of EBITDA by 2028. Selling wind generation stakes and rotating into regulated grids is deliberate: grid revenues are predictable and tariff-linked. The regulated grid business is planned to grow to a €70 billion regulated asset base by 2028, providing secure, predictable returns. That is a genuine improvement in earnings quality, not window dressing.
But the sheer volume of asset sales still matters. In April 2026, Iberdrola closed the sale of its Mexican business to Cox for $4.2 billion. Add the East Anglia Two proceeds and the Masdar co-investment in East Anglia Three, and the company is recycling tens of billions of euros across a single strategic cycle. Iberdrola has also said it expects to generate €52 billion in cash flow over the 2025 to 2028 period alongside its asset rotation and partnership plan. That coverage is what separates a capital recycler with a durable dividend from one leaning on disposals to paper over a gap.
How to Read the Scorecard
For income investors, the relevant metrics are not just yield and payout ratio. Watch whether operating cash flow, independently of asset sale proceeds, is growing. Watch whether the shift toward regulated networks lifts the proportion of earnings that do not depend on wind speeds or merchant power prices. The business mix of renewables and grids positions Iberdrola within the defensive utilities segment that often attracts income-focused investors, but defensive positioning only holds if the underlying cash generation is real.
The East Anglia Two sale, priced at a premium that implies strong institutional demand for UK offshore wind, suggests asset values remain firm. That is good news. The deal is in line with Iberdrola’s strategy of financing growth through asset sales and strategic alliances rather than issuing equity and diluting existing holders. So far, the dividend case holds. The watch item is what the company does with the proceeds: if they fund the grid expansion plan rather than plug operating shortfalls, income investors have little to worry about.
The Wealth Builder Takeaway
Utilities that recycle capital well can sustain and grow dividends without permanently shrinking the business. The discipline to distinguish between those two outcomes is what separates a long-term income holding from a slow-motion yield trap. Iberdrola’s direction looks right. The pace of asset sales means investors should keep checking the operating cash flow line, not just the headline payout.