Industrial booms are easiest to see in hindsight. The customs data released Monday from Seoul is an unusual exception: it lets you watch one happening in something close to real time.
South Korean exports rose 78.3% in the first twenty days of September compared with a year earlier. Adjusted for working-day differences, average daily exports rose 89.8%, up from 61.5% growth during the same period in August. The pace did not hold; it accelerated. Total outbound shipments hit $71.4 billion for the September 1–20 window, the highest ever recorded for the period, surpassing the previous record of $61.7 billion set in June, just three months earlier.
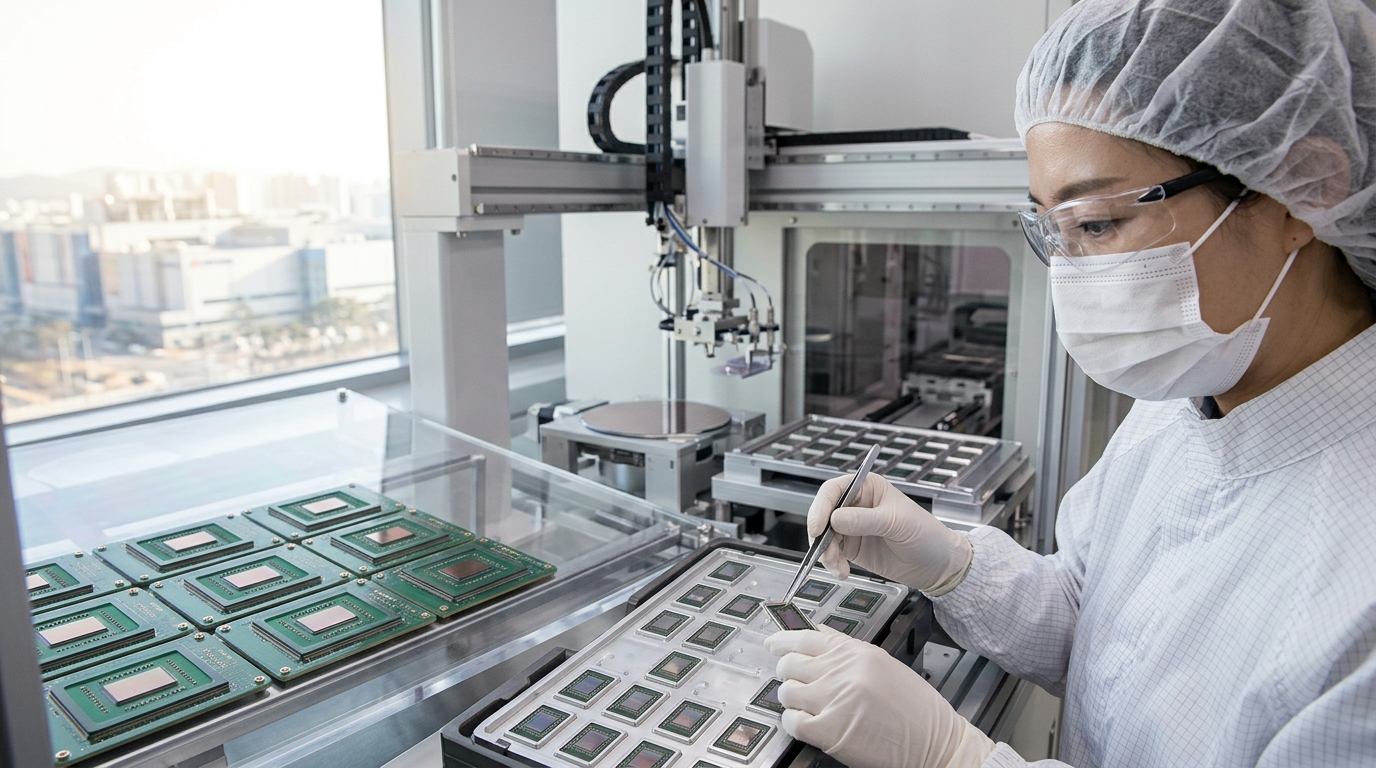
The engine is not a diversified export economy. South Korea shipped $34.12 billion of semiconductors in those twenty days, up 259.4% from a year earlier, meaning chips accounted for 47.8% of everything the country sent abroad. Imports rose 26.7% over the same period, leaving a trade surplus of $23.0 billion.
What This Data Actually Measures
South Korea’s customs flash releases are not survey data or analyst estimates. They are shipment records. That makes them among the cleanest high-frequency signals available on global AI hardware demand, and right now, that signal is pointing straight up.
Shipments to China more than doubled to $16.6 billion, while exports to the United States jumped 118% to $14.2 billion. Both destinations are absorbing chips at a rate that implies continued large-scale data center build-out, not inventory restocking. The distinction matters: restocking cycles end. Infrastructure construction cycles tend to run longer and finish less neatly.
Samsung Electronics and SK Hynix together control the vast majority of global high-bandwidth memory supply. SK Hynix has disclosed that it held 56.4% of the HBM market by revenue in the first quarter of 2026, and industry research has also put it around the mid-50% range for 2026. Every Nvidia GPU shipped to a hyperscaler carries HBM that almost certainly came from one of these two Korean factories.
The Mogul Mindset
Long-duration investors have seen industrial booms before: steel in the 1950s, semiconductors in the 1990s, shale in the 2000s. The pattern is consistent: demand accelerates, capacity follows with a lag, prices peak, then supply eventually catches up faster than expected. The question is never whether the cycle turns. It is how far along the runway you are when it does.
Gartner forecasts worldwide semiconductor revenue will reach about $1.6 trillion in 2026, up 92% from $809 billion in 2025, with memory as the primary contributor to growth. In the June quarter, Samsung Electronics and SK Hynix together were reported to have generated about 150 trillion won, roughly $104 billion, in combined operating profit, driven largely by AI memory demand. For the full year, SK Hynix alone is projected to earn more in profits than it generated across the prior 27 years combined.
Those numbers justify serious attention. They also demand serious scrutiny. If hyperscalers reduce or delay capital expenditures, demand for AI infrastructure components could slow materially. Customers sometimes place orders in anticipation of future demand, which can produce inventory corrections and order cancellations. The industry is already grappling with a capacity shortage that some analysts forecast could last up to two years, which means the supply response, when it arrives, could be substantial.
The Long-Term Verdict
The September customs data is not a buy signal for any ticker. It is something more durable: evidence that the physical infrastructure of the AI era is being built at a scale and speed that is still surprising even experienced observers. Samsung and SK Hynix sit at the center of that supply chain, as do their customers at Nvidia, Micron, and TSMC.
Disciplined investors do not chase the acceleration. They ask what the business looks like when the acceleration normalizes, and whether the competitive position that produced 259.4% export growth in twenty days survives the inevitable capacity additions ahead. In cycles this powerful, the hardest intellectual work is not identifying the boom. It is knowing what you are paying for the years that come after it.