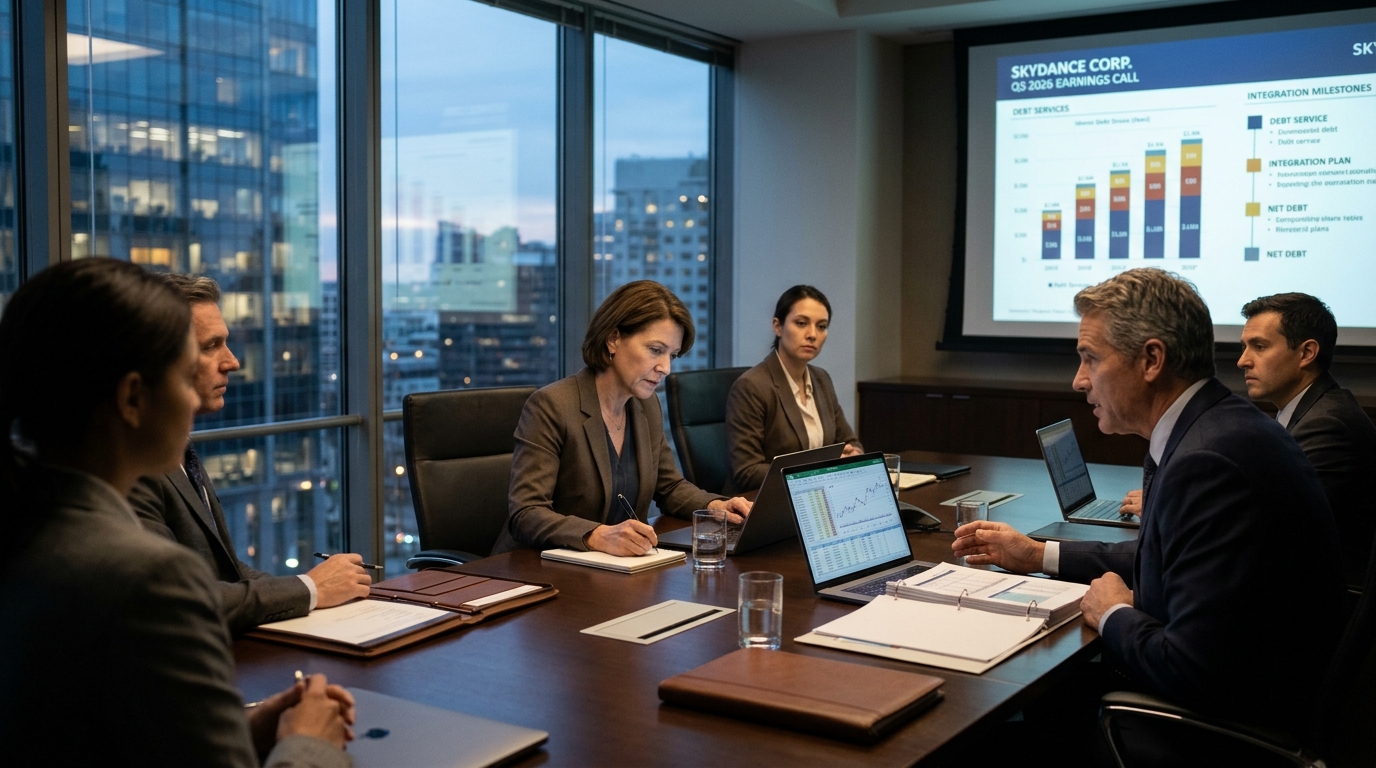
When Skydance Corporation (NYSE: SKYD) reports Q3 2026 results at 5:00 p.m. ET today, the quarter itself will be almost beside the point. The three months ending September 30 closed before the acquisition was completed on October 6, 2026, so the financials investors see tonight are still a pre-merger snapshot. What matters is everything management says after the numbers land.
This is the first time David Ellison and co-CEO Ynon Kreiz take analyst questions as operators of one of the largest media companies on earth. Paramount Skydance acquired Warner Bros. Discovery for $31.01666668 per share in cash. The asset list runs from HBO and Max to CNN, TBS, TNT, Paramount Pictures, CBS, Nickelodeon, and a dozen cable brands in between. The question that matters: how much of it stays?
The Debt Is the Story
Both credit agencies cite the notes’ lack of a Skydance guarantee and their position behind the company’s first-lien secured debt. Against that load, management has targeted at least $6 billion in run-rate synergies within three years. Independent credit analysis suggests that target alone is not enough. That analysis also assumes ongoing linear-TV EBITDA decline and does not rely on asset sales or equity issuance.
Linear television represents approximately 79% of 2026 estimated adjusted EBITDA excluding synergies, but falls to an estimated $5.3 billion over the forecast period even with revenue declines slowing to 6% to 7% a year, meaning synergies rather than the underlying business drive any improvement. That is a fragile foundation for a heavily secured debt load.
What Investors Need to Hear Tonight
Analyst estimates heading into this call are scattered. The company’s recent earnings trajectory has been volatile, with three upward EPS estimate revisions offset by eight downward revisions over the past three months. Revenue has shown more positive momentum. Skydance’s current price-to-sales ratio stands at approximately 0.31, signaling the market’s cautious outlook on future growth. The stock is currently trading at less than 1x sales, which makes it significantly cheaper to own than rivals including Netflix and Disney.
The valuation discount reflects uncertainty, not pessimism about content. The three things that could move SKYD off that discount: a credible asset-sale timeline, a first look at realized synergies in the combined structure, and a 2027 outlook that shows free cash flow covering interest costs without relying entirely on synergy projections that won’t fully materialize for years.
Bull Case
The combined entity owns two of Hollywood’s five major studios, two premier streaming platforms in Max and Paramount+, and sports rights spanning the NFL, the NBA on TNT, and the Olympics. Together, the company has committed to a minimum of 30 theatrical films per year. If Ellison can demonstrate even partial synergy delivery and name specific assets heading toward sale, the gap between 0.31x and 0.66x sales closes fast.
Bear Case
Divestitures of certain cable networks were discussed in the regulatory process, and the settlement framework includes conditions that constrain how the combined company negotiates certain cable channel fees. Any sale process for linear assets into a buyer market already flooded with declining-revenue cable networks will face tough pricing. In a bear scenario, the $5.0 billion revolver could be fully drawn in 2028 and Skydance would still need $2.6 billion of new debt to meet that year’s maturities, rising to $13.0 billion by 2030. That refinancing risk is real, and bond markets are already pricing it.
What to Watch at 5 p.m.
Three signals will tell investors whether the thesis is intact. First, any specificity on asset sales, particularly which linear cable networks are on the block and at what valuation. Second, the first read on how integration costs are tracking against the $6 billion synergy target. Third, whether management provides 2027 revenue guidance that holds up without assuming synergies flow at full speed. If all three are vague, the valuation discount has further to run.