Three software companies reported beats last week and watched their stocks fall anyway. Twilio tumbled 19% on Friday despite beating third-quarter earnings and revenue estimates, as investors weighed the outlook against elevated expectations. ServiceNow dropped about 26% and Fortinet fell about 22% as investors fixated on AI monetization and softer-than-expected forward numbers. Shopify reports before the open on Tuesday, November 3. The question is not whether the company will grow. It almost certainly will. The question is whether it has something the others lacked: a concrete story about where growth comes from next.
It does.
Wall Street expects about 35% EPS growth and 32% revenue growth to $3.74 billion. Shopify guided revenue in the range of $3.73 billion to $3.78 billion for the period, and the company has exceeded its revenue growth guidance in 2026 so far, including Q1, when it guided low-thirties revenue growth and delivered 34%. The base case is solid. The more interesting case sits one layer beneath the headline.
What the Meta Partnership Actually Means
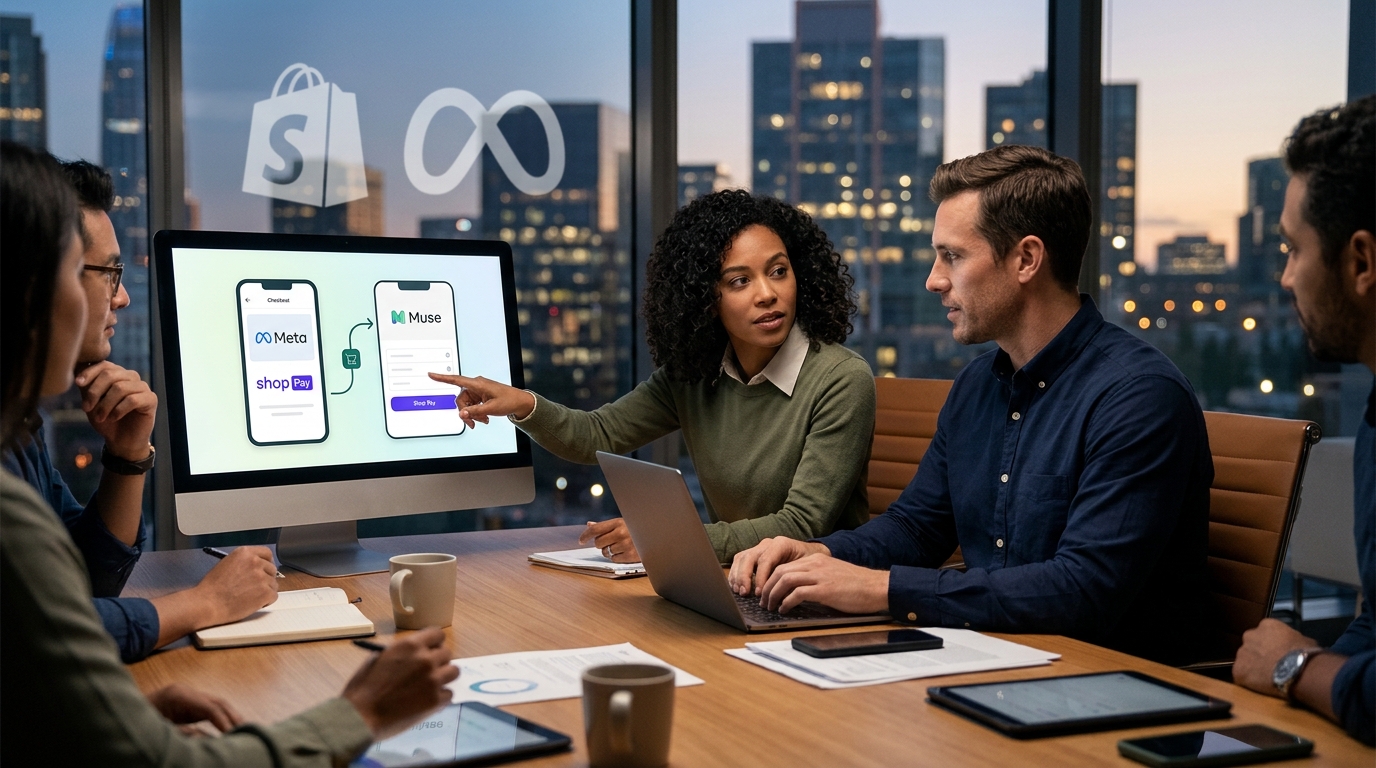
Meta has partnered with Shopify to enable a Shopify-powered checkout on Meta surfaces, including Muse when available, so shoppers can complete purchases without leaving the experience. Amazon, by contrast, has taken steps that limit AI agents from shopping on its platform. That asymmetry matters. Every order flowing through Muse can land on Shopify’s checkout rail, not Amazon’s.
Shop Pay surpassed $400 billion in lifetime accelerated gross merchandise volume in June, Shopify said on its Q2 earnings call. The bull argument is that Shopify is becoming the transaction layer for agentic commerce the way Visa became the transaction layer for the web: invisible, ubiquitous, and very hard to displace.
The Business Behind the Growth
Merchant solutions, primarily payment processing, grew 37% in Q2 but carry only about 38% gross margin. Subscription solutions grew 22% and retain roughly 80% margin. Faster payments growth compresses overall gross margin despite beating revenue guidance. That mix shift is why Shopify guided gross profit dollars to grow at only a mid-to-high 20s rate even as revenue targets run in the low 30s. Gross profit dollars, not revenue, is what Morgan Stanley weights most heavily.
Morgan Stanley maintained an Overweight rating and a $192 price target in a preview titled “3Q26 Preview – Delivering Against a Higher Bar.” The firm is optimistic. Its title is a warning too.
The Risks Are Real
At roughly 75 times 2026 earnings estimates, Shopify’s premium valuation leaves no margin for error on profitability. On the Q2 call, analysts pressed management on whether roughly 20% free cash flow margins are the new normal, and the company did not commit to that framing. Last quarter’s EPS of $0.421 beat the $0.404 consensus. If AI revenue is still in the “prove it” stage, investors tend to shrink the multiple, which can drag a stock lower even without a terrible quarter.
The fourth-quarter guide will carry as much weight as Q3 results. Morgan Stanley frames the holiday outlook as the decisive input for what comes next. A strong Black Friday outlook in the guide could reframe the whole story for year-end.
What to Watch Tuesday
Three numbers will determine whether the market rewards or punishes the quarter: gross profit growth (the mid-to-high 20s bar set in August), free cash flow margin (high teens to low 20s), and the Q4 revenue guide. The clearest signal on the Meta partnership will be whether Shopify starts disclosing any metrics tying AI agents to commerce activity, such as the share of Shop Pay checkouts initiated inside Muse or commentary on agent-driven GMV. If management quantifies even early Muse volume, the conversation shifts from valuation defense to valuation expansion.
Shopify is not just another software company reporting into a hostile market. It is the only major e-commerce platform that has made itself the preferred checkout for AI agents, with a concrete partnership and a working product. Whether Tuesday’s numbers justify roughly 75 times earnings is a different question. The structural position is one worth understanding before the market opens.