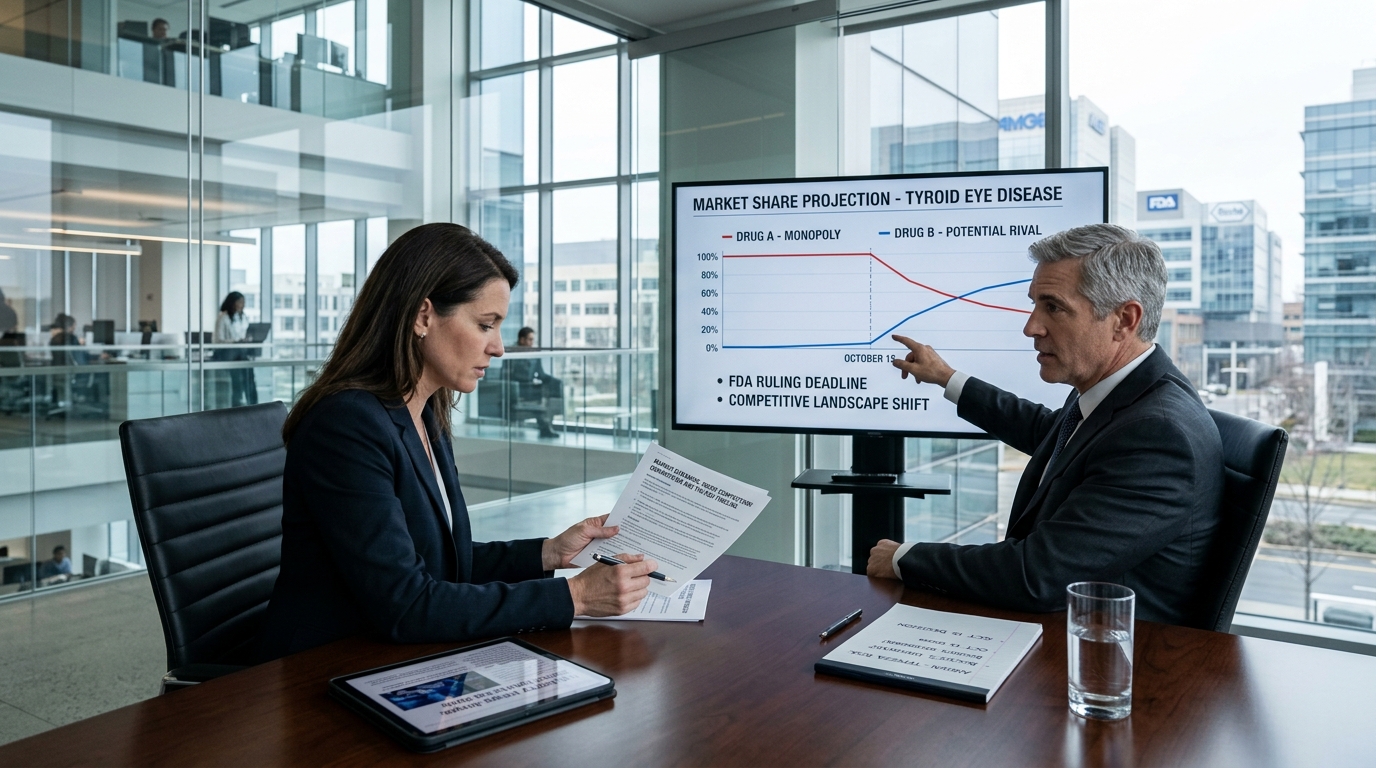
For years, Tepezza has effectively owned thyroid eye disease. No rival drug, no competing label, no pricing pressure. Tepezza (teprotumumab) has been the only FDA-approved treatment for TED since 2020, and that monopoly has been extraordinarily lucrative. Amgen, which acquired Tepezza through its Horizon Therapeutics deal that closed on October 6, 2023, reported about $1.90 billion of Tepezza sales in fiscal 2025. In the second quarter of 2026 alone, Amgen reported Tepezza sales rose 14% year-over-year to $576 million. That kind of trajectory, in a single rare-disease indication with no competition, is exactly what investors pay a premium to own. Thursday could begin to change it.
The FDA’s target action date is October 15, 2026 for Roche’s supplemental BLA seeking to expand Enspryng (satralizumab) into thyroid eye disease. If Roche wins approval, it would introduce a subcutaneous, self-administered option, which Roche has pitched as an at-home treatment alternative. That distinction matters. In its current approved form, Tepezza is administered by intravenous infusion, once every three weeks for eight infusions. Enspryng would offer patients a self-administered shot at home, a meaningful convenience advantage in a disease that already imposes substantial treatment burden.
The sBLA is based on results from two randomized, placebo-controlled global Phase 3 SatraGO studies assessing satralizumab in moderate to severe TED, which Roche has said enrolled a total of 258 patients from 19 countries. The data are not a clean sweep. Reported week 24 proptosis response rates were 49% and 53% across SatraGO-1 and SatraGO-2, and SatraGO-1 did not meet its predefined statistical significance threshold versus placebo. Against Tepezza’s Phase 3 benchmarks, Enspryng’s efficacy looks differentiated but not dominant. Still, the program reported improvements across measures beyond proptosis, including clinical activity score and double vision outcomes, which are the kinds of endpoints that can shape payer and physician behavior once contracting discussions begin.
What Amgen Is Doing About It
Amgen has not been standing still. In April 2026, the company announced positive topline Phase 3 results for a subcutaneous, on-body injector version of Tepezza in participants with moderate-to-severe active TED, reporting a statistically significant and clinically meaningful 77% proptosis response rate during the 24-week placebo-controlled period. The strategy is clear: answer the convenience argument before a competitor can own it.
The subcutaneous Tepezza data are strong. But the on-body injector formulation still requires an FDA filing and review cycle of its own. It is not yet approved. Between now and that approval, Roche could hold the clearest at-home convenience story in the indication.
The Pricing Arithmetic
The stakes are sharpened by how expensive Tepezza already is. Health technology assessments have estimated a full 24-week treatment course at roughly $215,175 per patient at the submitted price assumptions used in those reviews. At those prices, payers have been waiting years for a reason to push back on Amgen at the formulary level. A competing approved drug, even one with a narrower efficacy profile, hands them that leverage. The entry of a second branded therapy rarely ends in a price war, but it does reset the negotiating table.
Bull and Bear
The bull case for Amgen rests on Tepezza’s efficacy lead and entrenched use. Amgen reported the Tepezza on-body injector achieved a 77% proptosis response rate at week 24 versus 19.6% for placebo in its Phase 3 study. Enspryng’s comparable figure in its better-performing study was 53%. Physicians who have watched Tepezza work since 2020 are not rushing to switch. Patient retention in rare disease is sticky.
The bear case is structural. Once a second drug has a label, payer dynamics shift regardless of efficacy delta. TED is an autoimmune disease with published estimates placing prevalence around 155 out of every 100,000 people. That prevalence makes the addressable market worth fighting over. Roche is not entering casually.
What to Watch
The October 15 FDA target action date is the immediate catalyst. An approval does not hit Amgen’s next quarterly report in any measurable way. The impact plays out over 2027 as formulary negotiations cycle through. Watch Tepezza’s net selling price trajectory in Q3 and Q4 2026 results, and listen for any changes in Amgen’s commentary around the subcutaneous on-body injector filing timeline. That regulatory submission is the company’s best response, and any delay would extend the window in which Roche can lean on convenience in the marketplace.
Tepezza’s monopoly era is ending, on Thursday or eventually. The question for Amgen investors is how much revenue erodes before subcutaneous Tepezza arrives to stabilize the franchise.